Yes, you can short sale your house if you have a HELOC, provided the lenders whose liens must be released agree to the sale terms. The key issue is whether the HELOC lender will release its claim against the property—and whether you will still owe an unpaid balance afterward. For a sale in 2026, get those terms in writing before you commit to closing.
- Can I short sale my house if I have a HELOC? Yes, with the required lender agreements.
- A HELOC lien release does not automatically forgive your remaining debt.
- Shortsalesdoneright provides short sale processing and lender negotiation services; lenders decide whether to approve.
- Review both mortgage and HELOC approval terms with a qualified attorney before closing.
Why this matters
Your first mortgage lender's approval does not settle a separate HELOC lender's claim. A buyer needs the required liens cleared at closing, and you need to understand what debt remains afterward. Those are different questions.
Shortsalesdoneright helps homeowners compare a short sale with other options. Before choosing a path, separate your goal of selling the house from your goal of resolving the debt. A transaction that accomplishes the first does not automatically accomplish the second.
Can I short sale my house if I have a HELOC?
A HELOC does not automatically prevent a short sale. The sale needs an agreement that addresses the HELOC lien, along with the first mortgage and any other claims affecting title. Start by establishing who must approve what.
- Identify the liens. Ask your agent and title or closing professional to confirm the mortgages, HELOC, and other recorded claims affecting the property. Do not assume your latest mortgage statement shows every obligation.
- Request current account information. Obtain payoff information and contact details for each lender or servicer. A HELOC's borrowing limit is not the same as its outstanding balance or its payoff amount.
- Submit the proposed sale. Each lender reviewing a short payoff needs the proposed terms and the financial documents it requires. Confirm separate submission instructions rather than assuming the first mortgage lender handles everything.
- Resolve the HELOC terms. Establish what the HELOC lender requires to release its lien and what happens to any unpaid debt. The first mortgage approval must also permit the proposed distribution of sale proceeds.
- Match the closing documents. Have the closing professional check that the final settlement follows every applicable approval. Ask your attorney about any obligation that survives the sale.
Getting an offer is not the same as getting permission to close. Keep the buyer, agent, lenders, and closing professional working from the same proposed settlement.
A lien release and debt forgiveness are different
A lien gives the lender a claim against the property securing the loan. Personal liability concerns whether the lender can seek repayment from you. Releasing the property does not, by itself, establish that the borrower owes nothing further.
This distinction matters when the HELOC lender agrees to receive less than its full balance. An approval letter needs careful review even if it clearly authorizes the sale. Language about releasing a lien and language about releasing the borrower address different obligations.
| Written term | What it addresses | What you still need to check |
|---|---|---|
| Lien release | Removing the lender's claim against the property | Whether an unpaid balance remains enforceable |
| Release of personal liability | The borrower's responsibility for the remaining debt | Which borrowers and obligations the release covers |
| Repayment agreement | A separate obligation to pay an agreed balance | Whether you understand and can meet its terms |
Do not rely on a phone conversation or a general statement that the account is approved. Ask your attorney to explain the actual language before you sign.
For a 2026 closing, keep the final approval letters and settlement documents together. If a later account statement or collection notice conflicts with your understanding, those records give your attorney something concrete to review.
What if the same bank holds my mortgage and HELOC?
The same bank holding both accounts does not mean one approval covers both debts. Separate loans can have separate servicing teams, review requirements, and approval conditions. Identify each account explicitly in the proposed resolution.
Ask whether the written approval addresses both the first mortgage and the HELOC. A reference to the property address alone does not explain how every account will be treated. Confirm which liens will be released and which debts, if any, remain.
When the HELOC is a junior lien, the broader issues resemble those in a short sale involving a second mortgage. The guide to short sale options with a second mortgage covers that related situation. Your own loan documents and lender approvals still control your transaction.
How to prepare your HELOC short sale file
A useful file explains the proposed sale, your finances, and the accounts involved. The lender determines its required documents; use its current checklist rather than treating a general list as complete.
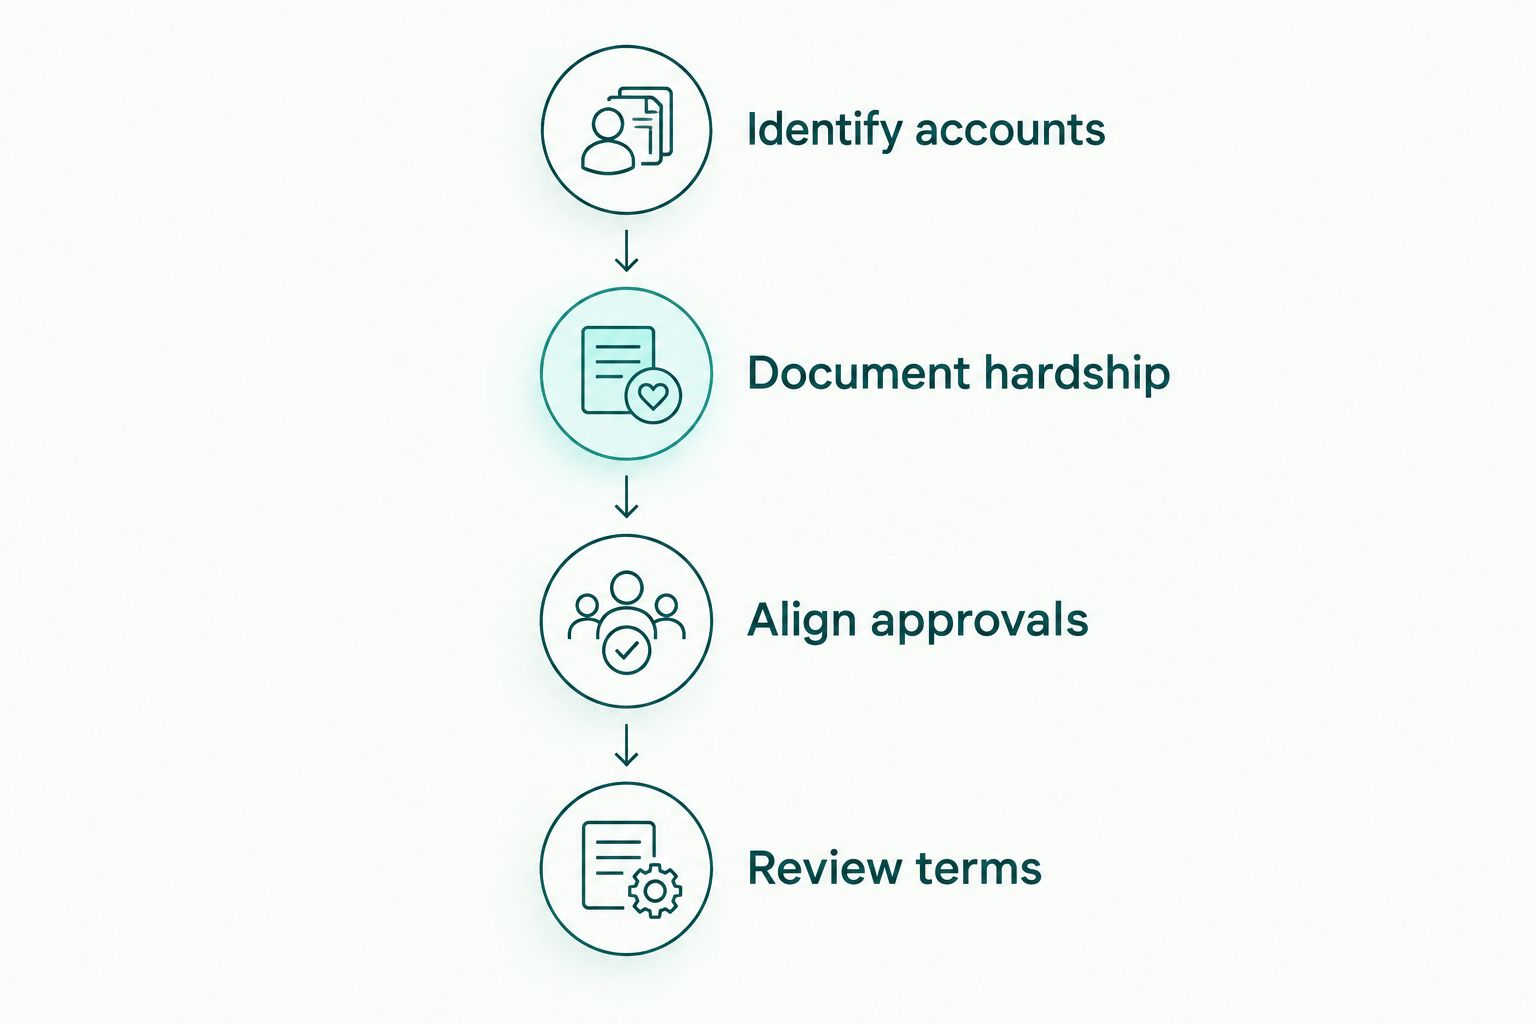
Identify accounts
Collect the first mortgage and HELOC statements, account numbers, and current servicer contact information. Include notices about transfers or collection activity. Tell your agent about the HELOC even if you have not borrowed from it recently.
Ask the closing professional how an open line of credit must be handled. Do not assume a zero statement balance means no recorded lien remains or that no release is needed.
Document hardship
Explain why the current mortgage obligations are no longer workable and why you are requesting a short sale. Keep the explanation factual. Support it with the income, expense, asset, and other records the lender requests.
Use current information for a 2026 application. If your employment or household finances change during review, tell the person coordinating the file so the lender receives an accurate picture.
Align approvals
Make sure the proposed settlement shows the intended treatment of each secured account. If one lender changes a condition, ask whether another lender must approve the revision. Do not leave conflicting requirements for closing day.
Review terms
Read the approval conditions before accepting the closing arrangements. Check the approved transaction, required releases, deadlines, and any continuing payment obligation. Send legal questions to an attorney and tax questions to a qualified tax professional.
Keep a written record of outstanding requests after each lender response. A request for more documents is not an approval, and a verbal update does not replace written closing terms. Ask who owns the next action and what document will confirm completion.
Why HELOC short sale requirements vary
The answer depends on the loan, the property, the proposed transaction, and applicable law. There is no single approval that applies to every homeowner.
- Lien position. Confirm where the HELOC sits among the claims against the property. Do not assume every HELOC is automatically in second position.
- Available sale proceeds. The proposed settlement determines what funds are available for the secured debts after the transaction's permitted deductions.
- Lender requirements. Each reviewing lender sets conditions for accepting a short payoff. An approval from one does not bind another.
- Your financial circumstances. The lender reviews the financial information required for its decision. Supply accurate records rather than trying to fit a generic hardship story.
- State law and loan terms. These affect questions about enforcement and unpaid balances. A qualified attorney must assess your specific situation.
- Other recorded claims. Additional liens introduce additional closing requirements. Identify them early through the title review.
Do not mistake a general explanation for an assessment of your HELOC agreement. The documents and applicable state law determine the legal consequences.
Will I still owe my HELOC after the short sale?
You can still owe an unpaid HELOC balance after a short sale unless the written agreement or applicable law eliminates that liability. A completed sale alone does not answer the question. Have an attorney review any language reserving collection rights or requiring further payments.
Ask a direct question: does this document release the lien, release personal liability, or do both? If you cannot identify the answer in the paperwork, resolve it before closing rather than relying on an informal explanation.
Can the HELOC lender stop my short sale?
A HELOC lender's refusal to release a required lien can prevent the proposed transaction from closing. That does not mean the lender controls every possible outcome; it means the current proposal lacks a necessary agreement. Ask what terms the lender requires, then have your agent and attorney assess the response.
Do not promise the buyer a closing based only on the first mortgage approval. The transaction needs compatible terms from every party whose consent or release is required.
Is a short sale the right option if I want to keep my home?
A short sale is an exit strategy, not a way to keep ownership. If staying is your priority, ask your mortgage servicers about retention options before committing to a sale. Address the HELOC as well as the first mortgage.
| Option | Best for | Potential benefit | Main limitation |
|---|---|---|---|
| Short sale | Homeowners seeking to sell despite a payoff shortfall | Creates a possible sale path with lender agreement | Requires approval and does not automatically erase remaining debt |
| Loan modification review | Homeowners trying to keep the property | Seeks a change to mortgage repayment terms | Requires lender approval and does not automatically resolve a separate HELOC |
| Deed-in-lieu review | Homeowners considering transfer to the lender | Provides another possible ownership-exit route | Requires lender acceptance and resolution of title issues |
These are options to evaluate, not promises of eligibility. A housing counselor can help you examine your budget and goals; an attorney can explain legal consequences. Compare the entire debt situation, not just the first mortgage payment.
Get help coordinating the lender review
Shortsalesdoneright is best for homeowners seeking short sale processing and lender negotiation help, not a guarantee of approval. The service also helps homeowners compare a short sale with other options. Lenders retain the approval decision, and legal and tax advice belongs with qualified professionals.
If you are ready to discuss your mortgage and HELOC, request help through the homeowner intake form on the website. Bring the account information for both loans so the conversation addresses the full situation.
Request help with your short sale
Discuss your mortgage, HELOC, and options before committing to a sale.
FAQ
Can I short sale my house if my HELOC is current?
Being current on your HELOC does not automatically rule out a short sale. The lenders still need to review the proposed transaction and agree to the required terms; do not stop making payments solely to seek eligibility.
Does first mortgage approval cover my HELOC too?
First mortgage approval does not automatically cover a separate HELOC. Confirm that each required account and lien is expressly addressed in the written approvals.
Will my HELOC disappear when the house sells?
Selling the house does not automatically eliminate your HELOC debt. Have an attorney confirm both the lien release and your responsibility for any unpaid balance.
Should I keep using my HELOC while requesting a short sale?
Do not treat the short sale request as permission to keep borrowing. Discuss further draws with your attorney and lender because additional borrowing changes the debt being reviewed.
Will I owe taxes if the HELOC lender cancels debt?
Canceled debt can have federal tax consequences, although exclusions or exceptions can apply. For debt canceled in 2026, ask a qualified tax professional to review the applicable rules and your circumstances.
Can Shortsalesdoneright guarantee my HELOC lender will agree?
Shortsalesdoneright cannot guarantee lender approval or forgiveness of an unpaid balance. It provides short sale processing and lender negotiation services; lender terms and state law vary.
Does applying for a short sale stop foreclosure?
A short sale application does not by itself guarantee that foreclosure stops. Confirm the status directly with the servicer and ask an attorney about any foreclosure notice or deadline.
One last thing
Ask for two answers before closing: what releases the property, and what releases you from the remaining debt? They need not be the same document or the same answer.
For your 2026 sale, make those questions part of the closing review—not a follow-up after ownership transfers. A sale approval is not a substitute for understanding what you will owe afterward.