Yes, you can receive relocation assistance connected to a short sale if the applicable program allows it and the required parties approve it; approval of the sale alone does not guarantee moving money. Request assistance before closing, because a payment received afterward is different from a new request made after the sale is complete.
- Can I get relocation assistance after a short sale? Yes, if approved terms provide for it; payment is not automatic.
- Request relocation assistance before closing and confirm the payment timing in writing.
- Moving assistance does not establish whether an unpaid mortgage balance is forgiven.
- Shortsalesdoneright helps homeowners compare a short sale with other options before deciding.
Can I get relocation assistance after a short sale?
Yes, but distinguish payment after closing from approval after closing. An approved relocation payment can have its own release conditions. If you have already closed without written assistance terms, ask the mortgage servicer whether any approved payment remains outstanding or any separate assistance is available. Do not assume the completed sale creates an entitlement.
For a 2026 short sale, use this sequence:
- Ask early. Tell the mortgage servicer that you need help with moving expenses and ask which assistance rules apply to your loan.
- Request written terms. Confirm eligibility, the approved payment, conditions, recipient, and release timing.
- Check closing instructions. Ask the closing professional how the assistance will appear in the transaction documents and reach you.
- Keep the records. Save the approval, final closing documents, and any payment confirmation.
Match that request to your short sale timeline. Assistance should be part of the closing discussion, not an assumption you discover while booking a move.
Why this matters
You need to know when money becomes usable, not just whether someone mentioned assistance. A moving company or rental deposit can require payment before an approved short-sale payment reaches you. Build your moving plan around confirmed funds and dates.
There is another distinction: approval to sell, permission to receive assistance, and treatment of the remaining mortgage debt are separate issues. A positive answer on one does not settle the others. Read each term before treating the transaction as a complete financial exit.
If you are planning a move in 2026, ask for a written payment schedule before making nonrefundable commitments. When the release date remains unconfirmed, keep that uncertainty visible in your budget.
Your next step depends on whether the sale has closed
The most useful question is not simply whether relocation assistance exists. It is whether assistance has been requested, approved, documented, and paid in your particular transaction.
| Situation | Best for | Main benefit | Limitation | Next move |
|---|---|---|---|---|
| Request before closing | Homeowners still negotiating a short sale | Assistance can be addressed with the transaction terms | A request does not guarantee approval | Ask the servicer for the applicable rules and written decision |
| Follow-up after closing | Homeowners checking an approved but unpaid payment | Focuses the inquiry on an existing written commitment | Payment remains subject to the actual conditions | Send the approval and closing records to the responsible party |
| Separate moving assistance | Homeowners needing help outside the sale | Keeps other possible support separate from lender negotiations | Separate eligibility rules apply | Ask a housing counselor about assistance to investigate |
Best for homeowners who have not closed: raise the request now. That gives your agent, servicer, and closing professional an opportunity to address the same terms before documents are finalized.
If you already closed, start with the paperwork rather than a new promise. Identify whether assistance was approved, who was responsible for releasing it, and what conditions still need confirmation.
How to ask for relocation assistance before closing
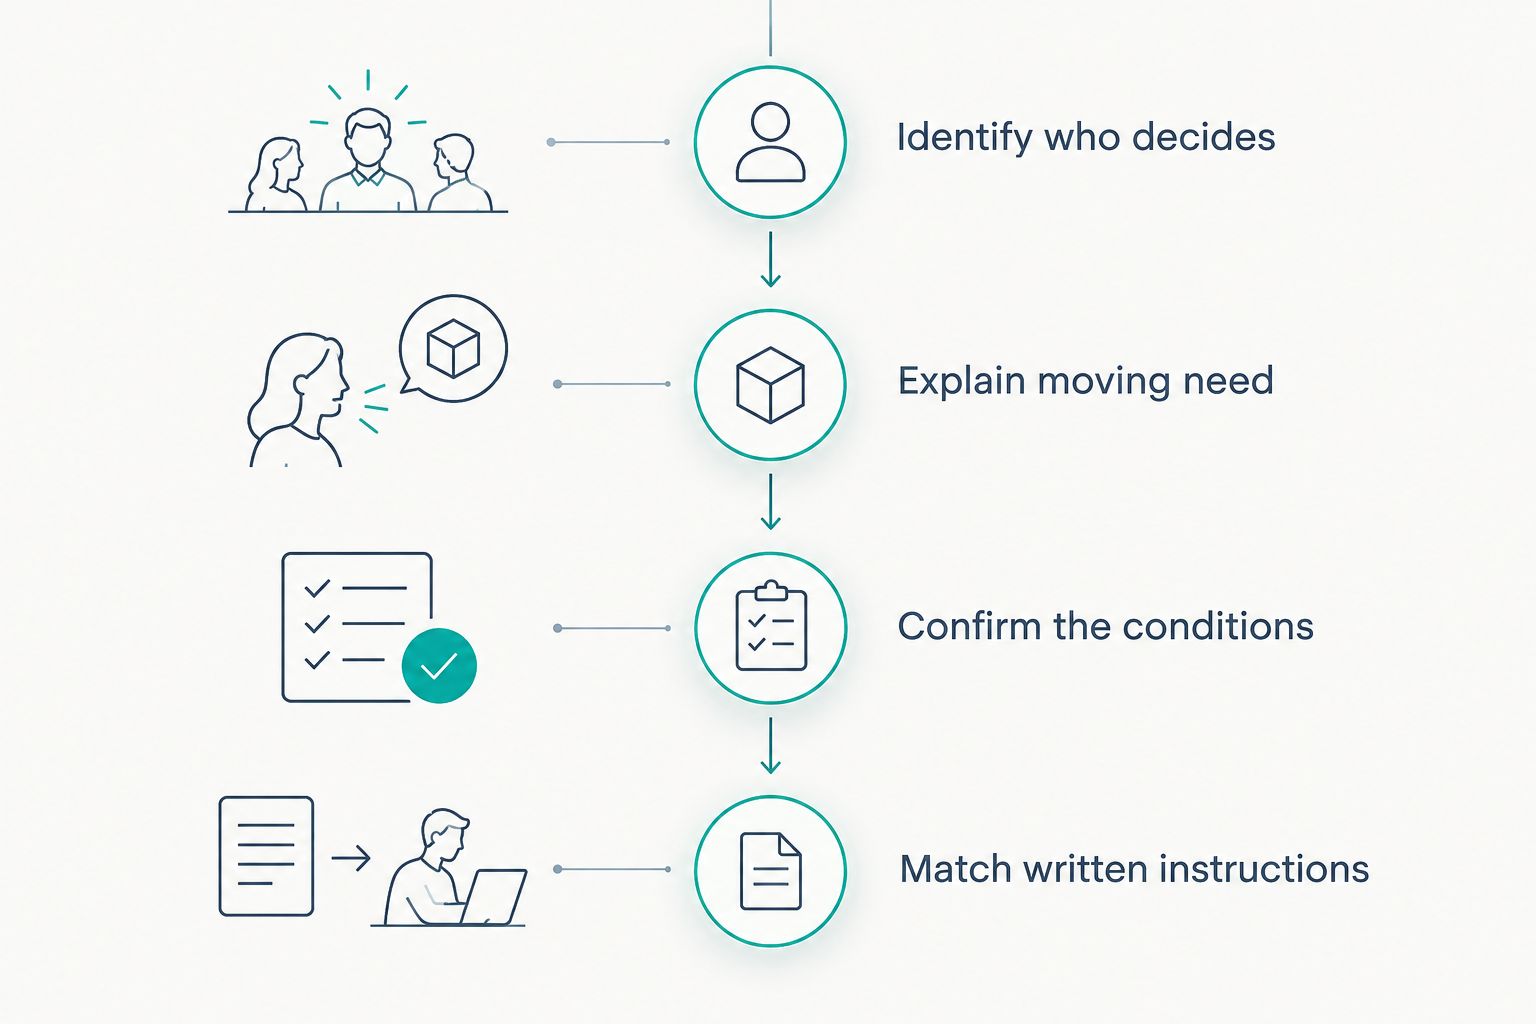
Identify who decides
Start with the company servicing your mortgage. Ask whether relocation assistance is available under the rules governing your loan and who must approve it. Your real estate agent can help coordinate the request, but an agent's expectation is not a lender decision.
Ask for the correct submission channel. Keep the response with your short-sale records so your request does not depend on someone remembering a phone conversation.
Explain the moving need
Describe the expenses you need help covering and your expected move. Keep the explanation factual and consistent with the financial information in your short-sale package. If the servicer requests supporting documents, ask exactly what it needs.
Do not assume a financial hardship automatically qualifies you for moving assistance. Ask for a separate answer about the assistance request, even when the hardship information is already on file.
Confirm the conditions
Ask what you must do to receive the payment. Questions about occupancy, property condition, required documents, and closing deadlines belong here—not after you have committed to a moving date.
Get clarification when a condition is unclear. Do not rely on a summary that leaves out when the money is released or what happens if the closing changes.
Match the written instructions
Ask your agent and closing professional to compare the assistance approval with the final transaction instructions. Confirm the recipient and payment method, and ask how the payment is documented.
For your 2026 closing, use the terms issued for your transaction rather than an older article or another homeowner's experience. A past payment to someone else does not establish your eligibility.
Keep a simple communication record as you complete these steps. Save the date, contact person's name, question asked, and written response. This makes it easier to distinguish a pending request from an approved payment.
Why relocation assistance varies
There is no single answer that establishes what every homeowner receives. Lender terms and state law vary. Confirm the rules for your loan and property rather than treating a general short-sale explanation as an approval.
These are the main points to verify:
- Loan rules. Ask which mortgage owner, insurer, guarantor, or assistance program sets the relevant requirements.
- Eligibility conditions. Confirm what the applicable rules require from you and whether you must submit supporting records.
- Transaction approval. Ask whether the assistance is explicitly included in the approved short-sale terms.
- Closing requirements. Check any conditions tied to documents, completion of the sale, or delivery of possession.
- Payment handling. Identify who releases the money, the recipient, and the event that triggers release.
Ask for a written explanation if assistance is denied. That helps you understand whether the issue is eligibility, missing information, or a condition of the proposed transaction. It does not guarantee a different decision.
What should I do if the short sale already closed?
Start by checking whether the relocation assistance was approved in writing. Locate the approval letter, assistance agreement if one exists, final closing statement, and relevant messages. Separate what was requested from what was actually authorized.
Then contact the party identified in the payment instructions. If the closing professional was assigned to disburse it, ask for the payment status. If the servicer controls the release, send the relevant records and request a written update.
Your follow-up should ask:
- Was the payment approved for this transaction?
- Were all release conditions satisfied?
- Who is responsible for issuing it?
- What action, if any, is still required from you?
If your 2026 sale closed without an approved payment, ask the servicer whether any post-closing option exists. Treat that as a new inquiry, not an established benefit. A housing counselor can also help you identify separate assistance to investigate.
Keep the payment issue separate from any dispute about the closing itself. If you believe a written commitment was not followed, ask a qualified attorney to review the documents and your options under applicable state law.
Is relocation assistance the same as debt forgiveness?
No. Relocation assistance and forgiveness of an unpaid mortgage balance are different terms. Moving money does not establish that a lender has released you from responsibility for a remaining balance.
Ask a qualified attorney to review the approval language addressing any unpaid debt. Ask a qualified tax professional about the tax treatment of the sale, canceled debt, and any assistance you receive. Do not infer those answers from the fact that the short sale closed.
The same caution applies to credit. Relocation assistance does not promise a particular credit-score result, and a short-sale approval does not establish how a future lender will evaluate you.
Can I use buyer money instead of lender assistance?
Do not arrange an undisclosed side payment to replace relocation assistance. Tell your agent and closing professional about any proposed buyer contribution and ask what approvals and disclosures are required.
A buyer's willingness to help does not establish that the payment fits the short-sale terms. Keep all proposed payments within the documented transaction and obtain the necessary approval before relying on them.
This protects the clarity of the deal. You should be able to identify every promised payment, its purpose, and where it appears in the authorized documents.
Get help without confusing assistance with approval
Shortsalesdoneright is a fit for homeowners who need short-sale processing and lender negotiation help while comparing their options. The service helps homeowners consider a short sale alongside other choices; it does not guarantee lender approval, moving assistance, debt forgiveness, or a specific credit result.
Before requesting help, gather your mortgage information, any existing approval letter, and your most recent closing or sale-status documents. Explain whether you are asking about a future assistance request or following up on money already approved. Those are different tasks.
Ready to discuss your situation? Use Shortsalesdoneright to find the appropriate homeowner intake form and request help. Keep legal questions with a qualified attorney and tax questions with a qualified tax professional.
FAQ
Can I get relocation assistance after my short sale has already closed?
You can follow up on assistance approved before closing, but a completed short sale does not automatically create a right to a new payment. Check the written terms and ask the servicer whether any post-closing option applies.
How much relocation assistance will I receive?
Your approved written terms determine any relocation payment; there is no universal payment to assume. Ask the servicer to confirm eligibility, the payment, conditions, and release timing before budgeting around it.
Will I receive moving assistance before I leave the house?
Do not assume assistance will arrive before you move. Ask the responsible party to confirm the release event and payment timing in writing before you commit to moving expenses.
Does every short sale include relocation assistance?
No, short-sale approval does not automatically include relocation assistance. Ask separately whether assistance is available and whether it has been approved for your transaction.
Does moving assistance mean the remaining mortgage balance is forgiven?
No, moving assistance does not establish forgiveness of the remaining mortgage balance. Have a qualified attorney review the debt terms and consult a tax professional about the tax consequences.
Can Shortsalesdoneright guarantee relocation assistance?
No, Shortsalesdoneright does not guarantee relocation assistance or lender approval. The service provides short-sale processing and lender negotiation help and helps homeowners compare a short sale with other options.
What should I do if an approved relocation payment has not arrived?
Contact the party responsible for payment and provide the written approval and closing records. Ask which release conditions remain outstanding and request a written status update.
One last thing
The payment date matters as much as the approval. An approved payment that arrives after you need a rental deposit does not solve that earlier cash need. Before setting your 2026 moving budget, write down when each expense is due and when approved assistance becomes usable.
Keep a copy of the final assistance terms somewhere you can access after moving. Your closing file should answer who pays, what triggers payment, and whom to contact if it does not arrive.