Yes. A short sale is an option to ask about if your mortgage lender is a credit union, but the credit union’s status does not establish your eligibility or guarantee approval. Approval to sell also does not automatically forgive any unpaid mortgage balance. For a 2026 decision, confirm who controls approval, what documents are required, and what happens to the remaining debt before accepting the terms.
- Is a short sale an option if my lender is a credit union? Yes, subject to lender approval.
- Credit union short sale eligibility depends on the mortgage, your finances, and the proposed sale—not membership alone.
- Get written terms covering the mortgage lien and any remaining debt before closing.
- Shortsalesdoneright helps homeowners compare a short sale with other options; lender approval is not guaranteed.
Why this matters
You need an answer about your mortgage, not a general answer about credit unions. A credit union can hold the loan itself or service a mortgage subject to another owner’s requirements. Start by identifying who makes the decision.
Shortsalesdoneright is a fit for homeowners who want help comparing a short sale with other options. You can request help through the appropriate homeowner intake form on Shortsalesdoneright. Processing assistance does not replace legal or tax advice, and no processor can promise the lender’s decision.
The practical question is whether a proposed sale resolves your housing problem on terms you understand. A sale that releases the house but leaves an unresolved debt requires a different decision from a sale with an express written release of that debt.
Is a short sale an option if my lender is a credit union?
Yes. Having a credit union mortgage does not, by itself, rule out a short sale. You still need permission to close a sale when the proceeds will not fully pay the secured mortgage debt and required releases cannot otherwise be obtained.
Use this sequence to find out whether the option fits your situation. Ask for the credit union’s current 2026 requirements rather than relying on another homeowner’s experience.
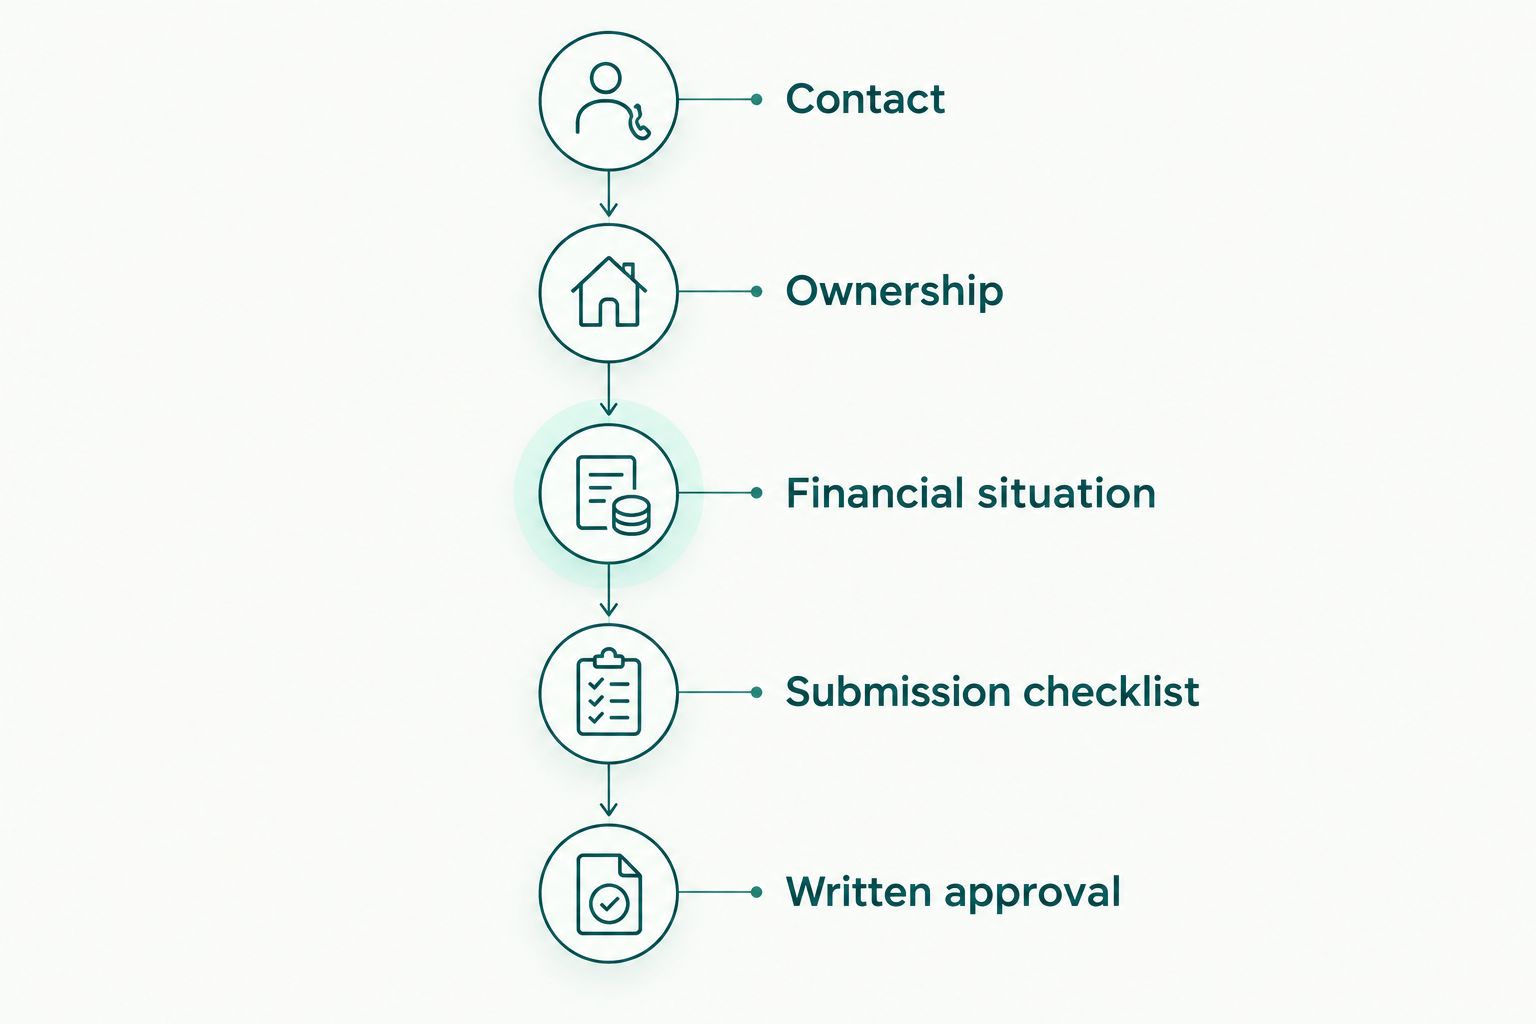
1. Contact the mortgage assistance department
Ask for the department that handles mortgage hardship, loss mitigation, or short sale requests. A general member-services representative is not necessarily the person who can explain mortgage approval requirements.
State your goal plainly: you are considering selling, and the expected proceeds will not cover the mortgage payoff. Ask how to open a short sale review and how to authorize your real estate agent or processor to communicate with the lender.
2. Confirm who owns and services the mortgage
Ask whether the credit union owns the loan or services it for another mortgage owner. Then ask whose approval is required and whether a mortgage insurer or another party must also consent.
Do not assume a local branch can approve the transaction. Knowing the decision-maker helps you understand which requirements apply and where unanswered questions need to go.
3. Explain your financial situation accurately
Describe why keeping the mortgage or paying the shortfall is not workable. Job loss, reduced income, divorce, or other financial changes need an explanation supported by the documents the lender requests.
Being underwater and being unable to sustain the mortgage are different issues. The lender needs enough information to evaluate your request; an estimated property value alone does not establish approval. Review the signs you might qualify for a short sale before deciding what questions to ask.
4. Request the exact submission checklist
Ask which financial statements, income records, account statements, hardship information, listing documents, and offer documents are required for your file. Confirm the submission method and whether anything needs updating during review.
Keep a copy of everything submitted. A confirmation that documents arrived is different from confirmation that the package is complete or that the sale is approved.
5. Review the offer and written approval separately
An accepted buyer offer is not the same as lender approval. The lender evaluates the proposed transaction, including the property value and the proceeds it would receive.
When approval arrives, compare it with the purchase contract and closing documents. Have your closing professional and, where needed, an attorney check the conditions before you commit to a closing that does not match your understanding.
Does it matter whether the credit union owns my mortgage?
Yes. Ownership affects whose requirements govern the short sale review. Servicing identifies who handles the mortgage account and communications; it does not necessarily identify the final decision-maker.
| Mortgage arrangement | What it means for your request | What to confirm |
|---|---|---|
| Credit union owns the mortgage | The credit union evaluates the request under its applicable requirements | Who has approval authority and what terms are available |
| Credit union services another owner’s mortgage | The servicer must work within the owner’s applicable requirements | Whether additional approval is required |
| Property has another mortgage or HELOC | Another secured creditor’s release must also be addressed | What each creditor requires to release its lien |
These are approval arrangements, not better-or-worse rankings. Your task is to identify everyone whose consent or lien release is needed for the proposed closing.
If you have another account with the same credit union, list it when asking questions. Do not assume the short sale request settles a separate loan or changes that account’s obligations. Ask a qualified attorney to review any account or loan provisions you do not understand.
Why credit union short sale decisions vary
There is no single approval rule for every credit union mortgage in 2026. These factors explain why a familiar institution or a neighbor’s completed sale does not predict your result:
- Mortgage ownership and requirements. The loan owner’s rules help determine what the servicer can approve.
- Your financial circumstances. The lender reviews the hardship and financial information required for the request.
- Property value and sale proceeds. The proposed transaction must be evaluated against the lender’s assessment of the property and expected recovery.
- Other liens. Another mortgage, HELOC, or other recorded claim can add a separate release requirement.
- Package completeness. Missing or outdated documents leave questions unresolved and can interrupt review.
- Approval conditions and state law. The written agreement and applicable law affect the obligations that remain after the sale.
Do not turn these factors into a self-approval checklist. They identify what needs review, not a formula that guarantees acceptance. Ask the lender to explain any outstanding requirement in writing so you can respond to the actual issue.
Should I pursue a short sale or ask to keep the home?
Start with your goal and what you can sustain. If you want to remain in the home, ask about retention options before treating a sale as the only route. If you need to leave, compare the terms of the available exit options.
| Option | Best for | Main benefit | Main limitation |
|---|---|---|---|
| Short sale | Homeowners who need to sell with insufficient proceeds to pay the mortgage | Creates a possible negotiated sale route | Requires approval; remaining debt needs separate attention |
| Loan modification | Homeowners seeking to keep the home with changed mortgage terms | Can address an unaffordable payment if approved | Does not accomplish a sale or guarantee sustainable terms |
| Repayment plan or forbearance | Homeowners asking about temporary payment difficulty | Can provide a framework for addressing a temporary disruption | Does not automatically erase missed payments or solve negative equity |
| Deed in lieu | Homeowners exploring a negotiated property transfer instead of a sale | Provides another possible exit to discuss | Requires acceptance and review of liens and remaining obligations |
None of these options is automatically best because the lender is a credit union. Compare the actual written proposal, not just the name of the program.
For your 2026 housing decision, distinguish temporary relief from a lasting solution. If your income has recovered, keeping the home deserves a different review than it does when the mortgage remains unaffordable. A housing counselor can help you examine the budget; an attorney can address legal consequences.
What should I check in a credit union short sale approval?
Check the treatment of the unpaid balance, not just permission to sell. A release of the mortgage lien allows the property to transfer without that lien under the agreed conditions. It is not automatically a release of your personal obligation to repay a remaining balance.
Before closing, get clear answers to these questions:
- Does the approval expressly address the unpaid balance?
- Does it require any payment or a separate repayment agreement from you?
- Are all required creditors providing the releases needed for closing?
- Does the approval identify a closing deadline or other conditions?
- Do the final closing documents match the approved transaction?
Do not rely on a reassuring phone conversation where the written terms say something different or leave the issue unanswered. Send the unclear language to your attorney before signing.
Lender terms and state law vary. A qualified attorney should explain any potential liability for the unpaid balance. A qualified tax professional should review whether canceled debt creates a tax issue under the rules applicable to your situation in 2026. Neither forgiveness nor a particular tax result should be assumed.
Can I request a short sale while my payments are current?
Yes, you can ask about a short sale while current on payments, but current status does not establish eligibility. Explain the financial problem and ask whether the lender reviews requests based on an anticipated inability to continue paying.
Do not miss payments merely to try to qualify. Ask about the available process first. Delinquency can create additional consequences without securing short sale approval.
Will a short sale request stop a scheduled foreclosure?
No. Do not assume submitting a short sale request stops a scheduled foreclosure. Confirm the status directly with the servicer and get any postponement in writing.
If you have received a foreclosure notice or sale date, contact a qualified local attorney promptly. Short sale discussions and foreclosure deadlines need attention at the same time; an open review is not a substitute for legal advice.
How do I get help with the credit union’s paperwork?
Ask who will prepare the package, communicate with the lender, and tell you when something is missing. Your agent handles the listing and sale; short sale processing is a separate coordination task that needs a clear owner.
Shortsalesdoneright provides short sale processing and lender negotiation services and helps homeowners compare a short sale with other options. For agents outsourcing processing, the service includes preparing the full short sale package, a dedicated point of contact, and weekly lender updates.
That support addresses paperwork and communication. It does not replace the lender’s approval, your agent’s role, or professional legal and tax advice. Before requesting assistance, gather your mortgage statement, any lender notices, and a plain explanation of what changed financially.
Request help with your next step
Use the homeowner intake form to request help comparing a short sale with other options.
FAQ
Can a credit union approve a short sale?
Yes, a credit union can approve a short sale when it has the required authority and accepts the proposed terms. If it services the mortgage for another owner, additional requirements or approval can apply.
Does being a credit union member guarantee short sale approval?
No, membership does not guarantee short sale approval. The mortgage requirements, financial circumstances, property value, and proposed transaction still need review.
Will my credit union forgive the rest of my mortgage after a short sale?
Forgiveness is not automatic after a short sale. Have a qualified attorney review whether the written agreement releases you from the remaining debt and how state law applies.
Can I short sell if I have a HELOC with the credit union?
A HELOC does not automatically rule out a short sale, but its lien and any remaining debt need separate review. Confirm what releases are required for closing, even when the same credit union holds both loans.
How long will my credit union take to approve a short sale?
There is no single approval timeline for every credit union short sale. Ask about the review process, outstanding documents, and any additional approvals required for your mortgage.
Will a short sale protect my credit score?
A short sale does not guarantee a protected credit score or a particular score change. Payment history, account reporting, and your broader credit file affect the outcome.
Who should I call first about a credit union short sale?
Start with the mortgage assistance or loss mitigation department handling your loan. If you have a foreclosure deadline, also contact a qualified local attorney promptly.
One last thing
Ask two separate questions: Will the lender release the property, and will the lender release me from the unpaid debt? Those answers are not interchangeable. Get both addressed before treating an approval letter as the end of the problem.
Keep the approval, final closing documents, and any separate debt-release agreement together. Written terms are what your attorney and tax professional need to evaluate the result—not a recollection of what someone said during negotiations.