A lender’s review of a short sale package has no single nationwide turnaround time in 2026; the useful estimate is the lender’s current timeline for your complete file. Confirm when the lender accepted the package as complete, what review remains, and when to follow up. Receipt of your documents is not approval, and the lender’s decision is separate from the time needed to close.
- How long does it take a lender to review a short sale package? Ask for the complete-file date and current review stage.
- Shortsalesdoneright short sale processing is best for agents who want package preparation and lender follow-up outsourced.
- A submission receipt confirms delivery, not completeness, approval, or a closing date.
- Track missing documents, valuation status, decision authority, and the next follow-up date separately.
How long does it take a lender to review a short sale package?
Use a file-specific estimate, not a promised national average. Ask the mortgage servicer—the company handling the loan—whether its estimate starts at submission, confirmation of a complete package, or assignment for review. Those are different milestones.
The MLS listing to short sale package workflow helps you separate preparing the file from waiting for a lender decision. Start your status log before submission so you can show what was sent and when.
| Reported status | What it establishes | What to ask next |
|---|---|---|
| Package received | The submission reached the lender’s intake channel | Has anyone checked it for completeness? |
| Documents missing | The lender needs additional information | Which documents, covering which periods? |
| Package complete | The lender considers its document requirements satisfied at that stage | What review remains? |
| Valuation pending | The lender is waiting on its property-value review | Is access or additional property information needed? |
| Decision issued | The lender has communicated its response | What conditions and deadlines apply? |
Keep the wording exact. If the lender says the package was received, do not report that the short sale is approved or that closing is imminent.
Why this matters
A buyer’s contract deadline and the lender’s review schedule are not the same thing. Your transaction needs both tracked separately. An expected response date is not a commitment that the lender will accept the offer.
For agents, the practical job is keeping the seller, buyer’s agent, and closing team informed without promising a decision. For homeowners, it is understanding what action is needed now and which deadlines require professional help.
Do not assume submitting a short sale package stops foreclosure activity. Lender terms and state law vary. If you have a foreclosure notice or sale date, ask the servicer about the account’s status and speak with a qualified attorney promptly.
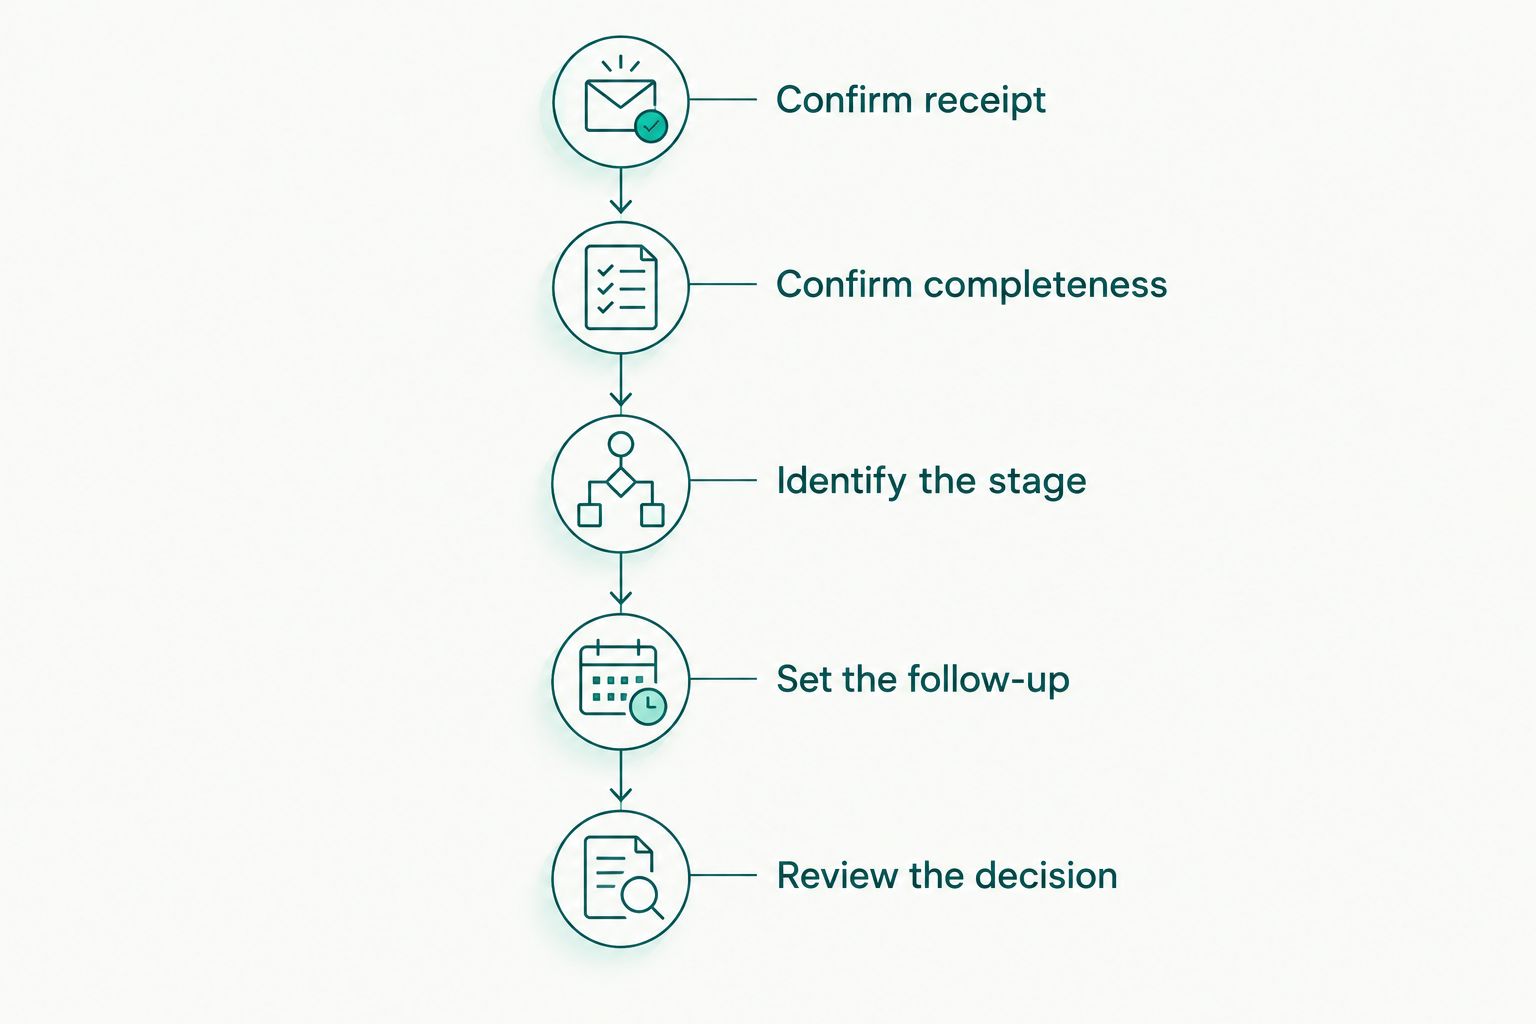
Follow these 5 steps to get a useful review estimate
1. Confirm receipt
Save the submission confirmation and record the delivery date. Identify the channel used, such as the lender’s designated portal or another method the lender instructed you to use.
Ask whether the documents are attached to the correct loan file. A successful upload establishes delivery; it does not establish that the lender has reviewed every document.
2. Confirm completeness
Request the lender’s current list of outstanding items. Ask for specific document names and the periods each document must cover rather than accepting a general request for updated financials.
Keep the lender’s checklist with your submission record. Requirements depend on the loan and review process, so a generic package checklist should not replace the lender’s instructions.
3. Identify the stage
Ask what work remains before a decision. The answer should identify the current task, such as document review, property valuation, or another required approval.
Then ask who owns the next action. If the lender needs something from the homeowner or agent, make that request visible immediately rather than leaving it buried in a status note.
4. Set the follow-up
Ask when the lender expects the next status update and which contact channel to use. Record that date as a follow-up commitment, not an approval deadline.
Use a repeatable question: What changed since the last contact, what remains open, and what is the next action? That produces a more useful answer than asking whether there is any news.
5. Review the decision
When a response arrives, read the written terms before announcing a closing date. Check the approved transaction terms, required conditions, and any stated expiration or completion deadlines.
Have a qualified attorney address legal questions about any unpaid balance. Ask a qualified tax professional about tax consequences. A short sale decision does not, by itself, answer every question about the homeowner’s remaining obligations.
Why short sale package review time varies
The useful question is not simply which lender is faster. It is what your particular file needs before the lender can make a decision. Ask about these factors rather than assigning each a guessed number of days:
- Package completeness. Missing signatures, unreadable files, or requested financial information leave open tasks. Ask for an itemized list and retain proof of your response.
- Property valuation. Ask whether the lender requires a property-value review and whether scheduling or access remains unresolved. Do not assume the contract amount settles the lender’s valuation question.
- Required approvals. Ask whether the servicer can make the decision or must obtain another party’s authorization. Record which approval remains outstanding.
- Additional liens. If another mortgage or lien affects the property, ask the closing professional what releases are needed. Do not assume the primary mortgage lender’s response resolves every claim.
- Changes during review. A revised offer, changed buyer, or updated financial information needs to reach the right reviewer. Ask whether the change requires additional review.
These are questions to resolve, not a formula for predicting approval. A clean package supports an organized review, but it does not require the lender to accept the transaction.
What should agents track in 2026?
Use a status log with 4 fields: current stage, open request, responsible person, and next follow-up date. Keep the underlying documents and correspondence with the transaction record. The log should summarize the file, not replace it.
A useful seller update states what the lender confirmed and what happens next. If nothing changed, say that plainly and identify the follow-up already scheduled. Do not turn silence into a positive forecast.
Separate the dates
Track 3 dates separately: submission, completeness confirmation, and next follow-up. Label a date as unconfirmed when you do not have confirmation. Do not quietly substitute the upload date for the complete-file date.
This distinction matters when someone says the package has been with the bank for a long time. The next question is whether the lender has been reviewing a complete file or waiting for a missing item.
Give the buyer’s side a usable update
Tell the buyer’s agent the confirmed review stage and any known action affecting the transaction. Handle contract extensions through the appropriate parties rather than assuming everyone will wait.
Protect the homeowner’s financial information. Share transaction status without forwarding personal financial documents to people who do not need them.
What should homeowners do while the lender reviews?
Keep requested documents accessible and respond through the agreed contact. If your income, household circumstances, or ability to complete the sale changes, tell the professional handling your file. Ask what the lender needs updated.
Do not make payment, moving, or legal decisions based only on an expected response date. A pending review is not permission to disregard loan obligations or notices. Get advice specific to your situation.
For a homeowner weighing options in 2026, the immediate question is whether the proposed sale still fits your circumstances. Ask your agent or processor to explain the pending tasks. Discuss legal deadlines with an attorney and tax questions with a qualified tax professional.
When should you ask for escalation?
Request escalation when a specific unresolved issue needs attention—not because a guessed timeline expired. Start with the lender’s stated follow-up process. Keep your request tied to the loan file and the action needed.
Useful reasons to ask for a supervisor or another designated contact include:
- The lender cannot locate documents you have proof of submitting.
- You receive conflicting instructions about the same requested item.
- A promised status update passes without an explanation.
- A known contract or legal deadline needs immediate attention.
State the submission date, the unresolved request, and the result you need. Avoid sending the same package repeatedly unless instructed; first ask how the lender wants the issue corrected.
If foreclosure activity is involved, escalation within the short sale department is not a substitute for legal advice. Confirm the account’s status separately and seek qualified help with deadlines.
When does outsourcing the follow-up make sense?
Shortsalesdoneright short sale processing is best for agents who want package preparation and lender follow-up outsourced. The service includes preparing the full short-sale package, a dedicated point of contact, and weekly lender updates.
That supports a clear division of work. The agent can coordinate the listing and transaction while the processor handles package preparation and lender communication. The trade-off is that outsourcing does not transfer the lender’s decision authority or remove the need for timely seller documents.
Shortsalesdoneright also helps homeowners compare a short sale with other options. Neither processing help nor negotiation guarantees lender approval, forgiveness of an unpaid balance, or a particular credit-score result.
To request help, visit Shortsalesdoneright and use the appropriate intake form for an agent or homeowner. Describe the current review stage and any deadline needing attention.
Get help with your short sale
Request package preparation and lender follow-up, or help comparing your homeowner options.
Does a complete package mean the lender will approve it?
A complete package means the lender has the documents it requested at that stage; it does not mean approval. The lender still needs to evaluate the proposed transaction and communicate its decision.
Ask whether further documents can be requested during review. Keep the distinction between document acceptance and transaction acceptance clear in every update.
Is the review timeline the same as the closing timeline?
The review timeline and closing timeline are separate. A written response can contain conditions that must be addressed before the transaction can close.
Coordinate the approval terms with the closing professional and the other transaction parties. Do not schedule a move solely around an informal estimate of when the bank will respond.
FAQ
How long does it take a lender to review a short sale package in 2026?
There is no single nationwide turnaround time for a lender to review a short sale package in 2026. Ask the servicer for its estimate after it confirms the file is complete, and identify any remaining review or approval steps.
When does the lender’s short sale review clock start?
Ask the lender which milestone starts its stated review period. Document receipt, completeness confirmation, and assignment for review are different events, so record the exact milestone the lender uses.
Does a submission confirmation mean my short sale package is complete?
A submission confirmation establishes delivery, not completeness. Request confirmation that the lender has checked the package and ask for an itemized list of anything still required.
Can a short sale processor guarantee a faster decision?
A short sale processor cannot guarantee when the lender will decide or whether it will approve the sale. Processing support organizes documents and follow-up; the lender retains decision authority.
Should I stop making mortgage payments while the package is under review?
Submitting a short sale package does not authorize you to stop making mortgage payments. Ask your servicer about your obligations and speak with a qualified professional before making decisions that affect your loan.
Does submitting a short sale package stop foreclosure?
Do not assume submitting a short sale package stops foreclosure. Lender terms and state law vary; confirm the account’s status with the servicer and take foreclosure notices to a qualified attorney promptly.
Does short sale approval mean I will not owe the remaining balance?
Short sale approval does not automatically establish that an unpaid balance is forgiven. Have a qualified attorney review the written terms and consult a qualified tax professional about potential tax consequences.
One last thing
For a short sale under review in 2026, ask this before asking for a decision date: What exact action must happen next, and who is responsible? An answer gives you something to resolve. An unsupported countdown does not.
Keep the written response with your file. Your strongest update is a confirmed milestone and a named next action—not a promise the lender never made.