Yes—if the mortgage servicer accepts pre-offer submissions, a real estate agent can submit the seller’s short sale documents before a buyer makes an offer. That starts the review the servicer permits; it does not approve a sale, and an offer-dependent review still requires the buyer’s contract and transaction details.
- Can a real estate agent submit a short sale package before an offer comes in? Yes, if the servicer accepts it.
- Pre-offer submission is not transaction approval; confirm what the mortgage servicer will review without a contract.
- Prepare seller documents early, but follow the servicer’s current submission checklist.
- Shortsalesdoneright short sale processing fits agents who want package preparation and lender follow-up outsourced.
Why this matters
Preparing a file, submitting a file, and obtaining approval are different milestones. An agent who treats them as interchangeable can give a seller or buyer the wrong expectations.
For a 2026 listing, confirm the servicer’s current process before describing the property as being under short sale review. Use the MLS listing to short sale package workflow to connect listing preparation with document collection. Keep marketing responsibilities separate from the lender’s decision.
Your immediate goal is practical: establish what can happen before an offer, prepare the accepted documents, and identify what must wait. That gives you a clear next action without promising approval.
Can an agent submit a short sale package before an offer comes in?
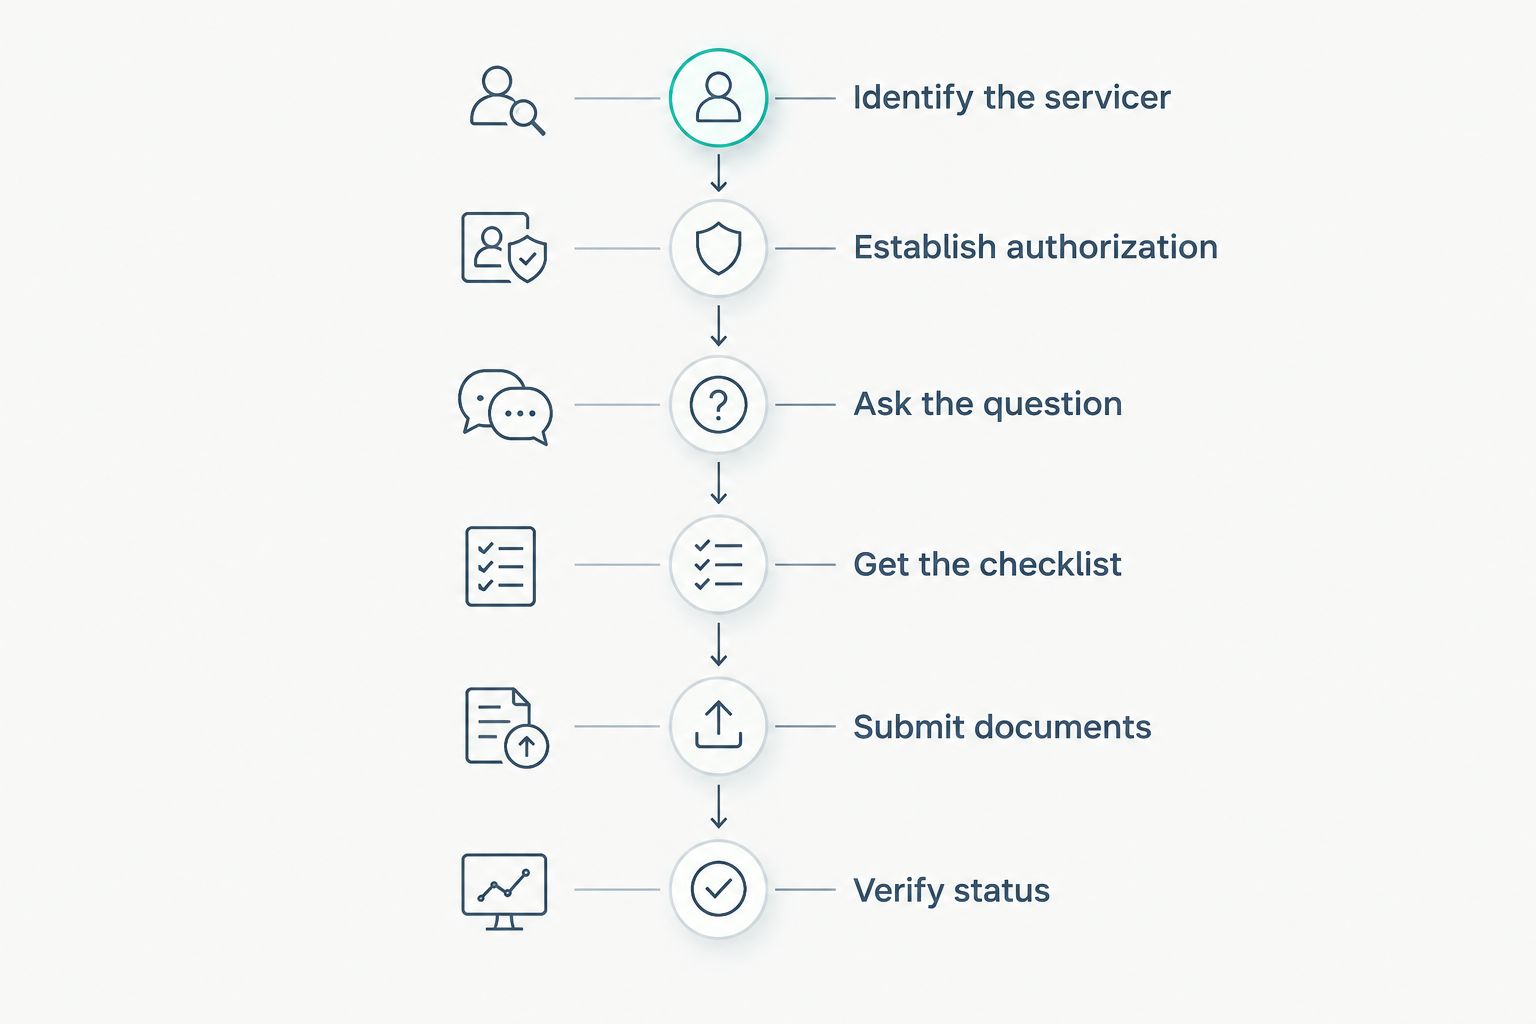
Yes, where the servicer’s process allows it. Start with these steps rather than sending a generic packet and assuming a review has begun.
- Identify the servicer. Contact the company handling the mortgage account and ask for its short sale or loss mitigation instructions. Confirm you have the correct department and submission channel.
- Establish authorization. Ask what signed permission the servicer requires before discussing the seller’s loan with you or a processor. A listing agreement does not replace whatever account authorization the servicer requests.
- Ask the exact pre-offer question. Find out whether the servicer accepts seller documents without an executed purchase contract. Ask what review, if any, those documents will trigger.
- Get the applicable checklist. Confirm the forms, supporting records, signatures, and submission method. Separate seller documents from items that depend on a specific buyer or transaction.
- Submit only through the accepted channel. Retain the upload confirmation, transmission receipt, or other acknowledgment. Record the submission date and the documents included.
- Verify the file’s status. Ask whether the documents were received, whether anything is missing, and whether the file is actually under review. Record the next required action.
A transmission receipt proves delivery, not approval or completeness. Follow up on the status the servicer assigns to the file rather than the status you expected.
What can you prepare before an offer?
You can organize the seller’s side of the file while confirming the servicer’s requirements. Early preparation is useful even when the servicer will not accept a submission until a contract exists. The limitation is document currency: records collected early can need updating before review.
Use the servicer’s 2026 checklist as the controlling document. The following categories are a preparation guide, not a universal submission requirement.
| File component | Before an offer | What still needs confirmation |
|---|---|---|
| Seller authorization | Obtain the permission the servicer requests | Required wording, signatures, and authorized contacts |
| Hardship explanation | Help the seller organize an accurate account | Whether a particular form or supporting evidence is required |
| Financial records | Collect the records requested for the seller’s circumstances | Which periods and document types the servicer accepts |
| Listing information | Organize the listing agreement and available marketing information | Whether the servicer requests them at this stage |
| Purchase contract | Cannot supply an executed buyer contract before one exists | Whether the servicer requires it to open or advance review |
| Transaction estimate | Identify the information needed for preparation | What must be updated when actual contract terms are available |
For a closer document check, use the guide to documents to include in a short sale package. Match every item to the actual request; a larger packet is not automatically a more complete packet.
Ask the seller to provide accurate records through an appropriate secure channel. Do not alter a hardship explanation to fit an assumed approval formula. If a requested record does not apply, ask the servicer how to document that rather than leaving an unexplained gap.
Pre-offer submission: best for accepted early review
Best for: Agents whose servicer confirms it accepts documents before an executed purchase contract.
The benefit is a defined early task: you can deliver the accepted seller information and identify outstanding requests while marketing continues. Ask the servicer to explain exactly what the submission starts. It might be document intake rather than a decision about selling terms.
The drawback is rework. Seller circumstances and supporting records can change before an offer arrives. Keep the seller informed that additional documents or updated signatures can still be requested.
Do not describe pre-offer acceptance as an approved short sale. Any preliminary guidance must be read according to its actual written terms.
Preparation without submission: best for contract-first files
Best for: Agents whose servicer requires an executed contract before accepting or advancing the short sale request.
Prepare the seller documents and keep a clear list of offer-dependent items. This approach respects the servicer’s process while avoiding a scramble to begin basic collection after the seller signs a contract.
The limitation is equally clear: an organized folder is not an active lender review. Tell the seller what is ready, what remains outstanding, and what event allows submission. Do not report that the bank is reviewing the short sale when the file has not entered review.
These routes are not competing shortcuts. Use the route the servicer accepts, not the route that sounds faster.
Why pre-offer submission rules vary
There is no single nationwide intake checklist for every short sale. In 2026, build your submission plan around the actual mortgage account and these factors:
- Servicer procedures. The servicer determines the intake channel, required authorization, and documents needed for its process. Confirm those instructions directly.
- Loan and investor requirements. Ask which requirements govern this mortgage and whether a particular short sale process applies. Do not transfer assumptions from another listing.
- Review stage. Opening an inquiry, reviewing the seller’s circumstances, and evaluating a purchase contract are different tasks. Ask which task can begin without an offer.
- Document currency. Ask how current the financial records and signed forms must be when submitted and reviewed. Record any update request.
- Other secured debts. Identify additional mortgage or lien issues early. Approval from one creditor does not establish that every claim against the property is resolved.
- Foreclosure status. An existing notice or sale date creates a separate issue to address immediately. Do not assume document submission suspends foreclosure activity.
Lender terms and state law vary. Refer questions about foreclosure rights, remaining debt, or legal deadlines to a qualified attorney; refer tax consequences to a qualified tax professional.
What should you tell the seller before an offer arrives?
Tell the seller what has actually happened: documents are being prepared, documents were delivered, or the servicer confirmed a particular review status. Avoid compressing all those stages into “the short sale is underway.”
A useful status update identifies the completed task, the outstanding request, and who owns the next action. If the servicer has not confirmed receipt or completeness, say that plainly. Clear reporting reassures the seller without creating a promise you cannot control.
For your 2026 transaction notes, keep a dated record of each contact and request. Include the department contacted, the instructions received, and any written confirmation. A future handoff should not depend on someone remembering a phone conversation.
If the seller is still deciding whether to leave the property, distinguish that decision from package preparation. A short sale is not automatically the right outcome simply because the file can be opened. The homeowner should understand other available paths and seek advice appropriate to their circumstances.
Does submitting early mean the lender will approve the offer?
No—early submission does not approve a future purchase contract. The servicer still needs whatever transaction information its process requires, and the proposed sale must satisfy the applicable review.
When an offer arrives, check the contract and requested supporting items against the current checklist. Update estimates and seller records as required. Do not assume information submitted earlier remains sufficient or that a new offer can simply be attached without further review.
Any written approval needs careful reading. Confirm the approved transaction terms and conditions rather than relying on a verbal summary. The seller should obtain qualified advice about any language addressing an unpaid balance.
Should you wait for an offer before contacting the servicer?
No—you can ask about the process before an offer exists. Early contact lets you confirm authorization requirements, document instructions, and whether pre-offer review is available.
Contact does not mean the seller has qualified or that a sale will be approved. It establishes the next permitted step. That distinction is especially important when the seller has already received foreclosure-related notices: address those notices separately with qualified legal help.
When to hand off package preparation
Shortsalesdoneright short sale processing is best for agents who want package preparation and lender follow-up outsourced. The service includes preparing the full short sale package, a dedicated point of contact, and weekly lender updates.
The benefit is a defined processing contact while you manage the listing and buyer-side work. The boundary remains the same: Shortsalesdoneright does not control lender decisions, and processing support does not replace legal or tax advice. The seller still needs to supply accurate information and complete required signatures.
Ready to request help? Use the agent intake form on the website to explain the listing’s current stage, whether an offer exists, and any known foreclosure notices. Separate confirmed facts from assumptions about approval.
Request short sale processing help
Use the agent intake form to describe your listing and request processing support.
FAQ
Can I start a short sale package without a buyer?
Yes, you can prepare the seller’s documents without a buyer. Whether you can submit them or begin review depends on the mortgage servicer’s process.
Does the lender need an offer before reviewing a short sale?
The servicer’s requirements determine whether review can begin without an offer. Ask which documents it accepts before a contract and which review stage those documents start.
Does submitting a short sale package stop foreclosure?
Do not treat submission as a foreclosure stop. Confirm the account’s foreclosure status with the servicer and get legal advice about notices, deadlines, and available protections.
What documents should an agent collect first?
Start with the servicer’s authorization requirements and current document checklist. Collect the requested seller, hardship, financial, and listing information rather than relying on a generic packet.
Can a short sale processor work on a listing before an offer?
A processor can help prepare the seller’s file and confirm submission requirements before an offer. Shortsalesdoneright provides package preparation and lender negotiation services; lender rules still determine when review can begin.
Is a pre-offer submission the same as short sale approval?
No, a pre-offer submission is not approval of a sale. Confirm the exact status in writing and distinguish document intake from approval of transaction terms.
Should I use a short sale checklist from another transaction in 2026?
Use the current checklist for the actual mortgage account in 2026. A prior transaction’s checklist can help you organize questions, but it does not establish this servicer’s requirements.
One last thing
Ask what happens next—not just whether you can upload documents. A portal that accepts a file does not tell you which review has started. Before ending your next servicer call, confirm the file’s status, the outstanding items, and the action required to advance it.