
Military homeowners’ short sale planning is the process of seeking lender approval to sell for less than the mortgage payoff, with the aim of resolving an underwater property before or after a military move. This 2026 guide explains how permanent change of station (PCS) orders, relocation expenses, loan type, and lender terms affect your next move.
- Searching military short sale pcs orders? PCS orders document your move; they do not guarantee lender approval.
- Shortsalesdoneright is best for military homeowners seeking short-sale processing and lender negotiation support.
- Compare keeping, renting, and selling before committing to a short sale on an upside-down mortgage.
- For a VA-backed mortgage, ask about remaining liability and future entitlement before accepting written terms.
Why short sale planning matters for military homeowners
PCS orders create a reporting deadline, not a lender approval deadline. Your household can face moving expenses and housing obligations at the next duty station while still carrying the existing mortgage. A sale that needs lender approval adds another decision-maker to that schedule.
Treat your relocation plan and your property plan as separate projects. You need a place to live even if the sale has not closed. You also need someone responsible for the property, lender requests, and closing documents after you leave.
For homeowner support, Shortsalesdoneright provides short-sale processing and lender negotiation services. That support addresses the lender process; it does not replace legal advice or guarantee approval.
In 2026, start with the actual loan and household finances rather than a general military eligibility checklist. PCS orders explain why you must move. The lender still needs to evaluate the proposed sale under the rules that apply to your mortgage.
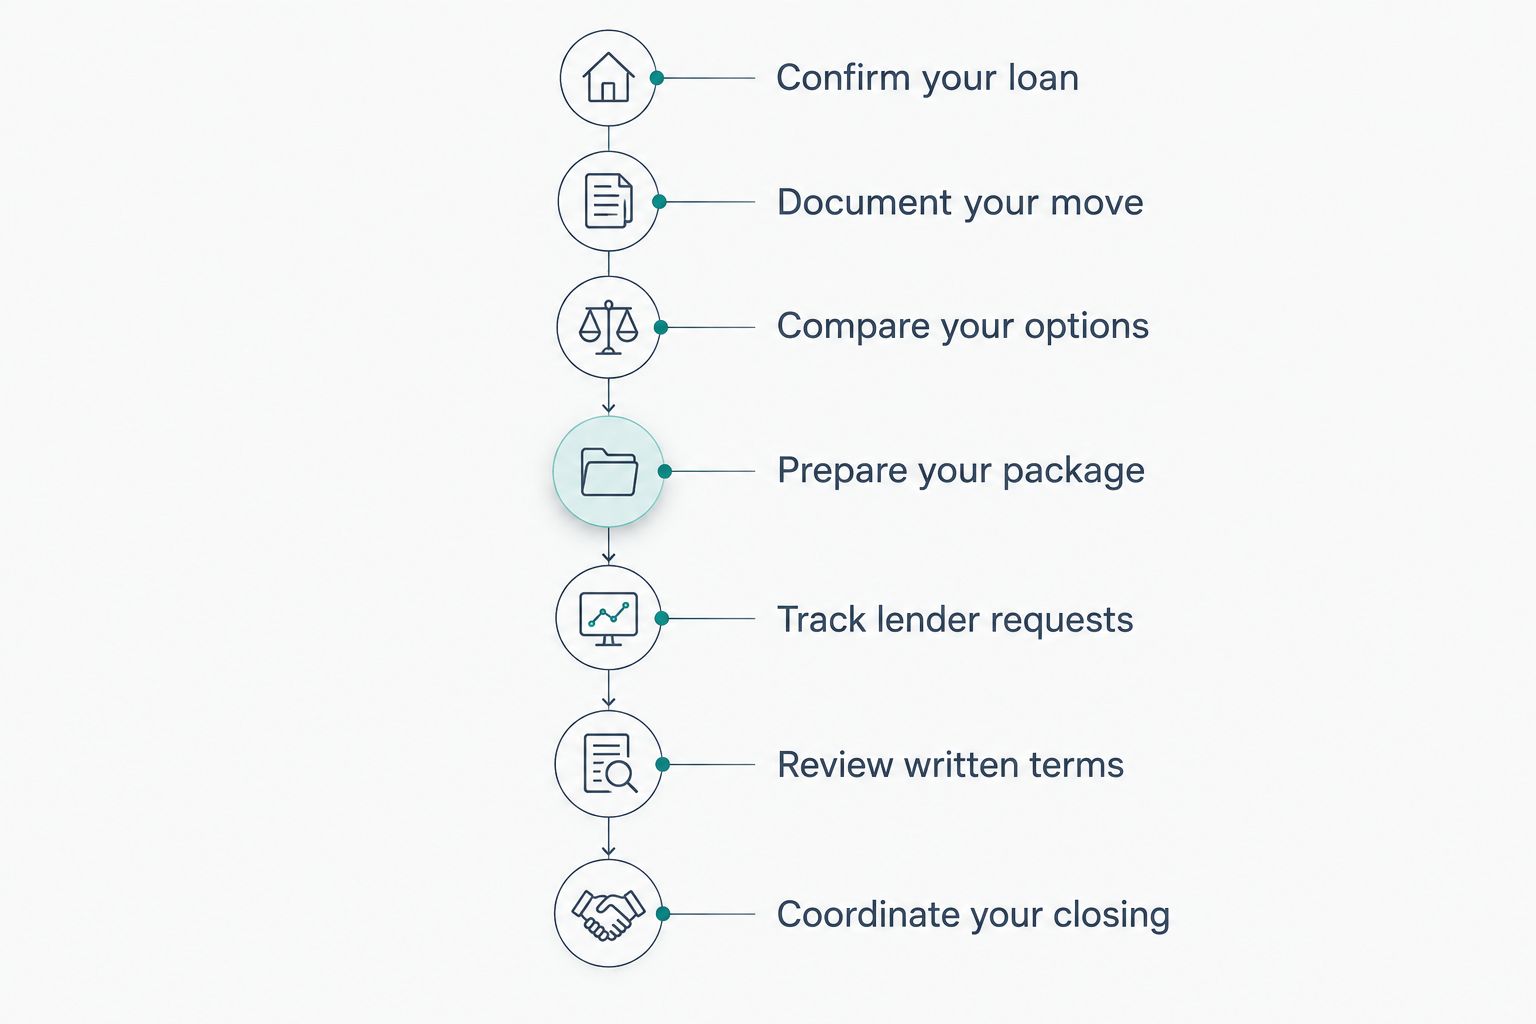
Build your military short sale plan
Confirm your loan
Identify who services your mortgage and whether it is VA-backed, FHA-insured, conventional, or another loan type. Military service does not mean every mortgage is a VA loan. Ask the servicer which short sale requirements apply to your specific account.
Compare the estimated sale proceeds after selling expenses with the mortgage payoff. A listing price alone does not show whether you can cover the debt. Include any second mortgage or other recorded lien that needs attention before closing.
Create 1 loan record containing the account details and the people responsible for responding. This keeps a spouse, agent, and processor working from the same information.
- Request a current payoff statement from the servicer.
- Identify every mortgage and known lien on the property.
- Ask who reviews short sale requests for your loan.
- Record contact details and authorization requirements.
Document your move
Explain the connection between your PCS move and the financial problem. The orders establish the move; your financial records explain why keeping or selling the home through a standard transaction is not workable.
Prepare 2 household budgets: your current expenses and your expected expenses after relocation. Use documented figures where you have them. Mark estimates clearly rather than presenting an anticipated housing expense as an existing bill.
If your income continues, say so. A hardship explanation should describe your actual circumstances, not suggest unemployment or a pay reduction that did not happen. For a 2026 PCS move, use current orders and explain any amendments that change your schedule.
- Include PCS orders using the servicer’s secure submission method.
- State your reporting date and expected move date.
- Explain overlapping housing and relocation obligations.
- Identify who can answer questions while you travel.
Compare your options
Do not assume a short sale is the only answer because the mortgage exceeds the likely sale proceeds. Compare keeping the property, renting it, selling with funds brought to closing, requesting mortgage assistance, and seeking a short sale.
Build the rental comparison around net income, not advertised rent. Account for management, maintenance, insurance, vacancy, and mortgage payments. Ask your insurance provider and servicer about requirements before changing the property’s use.
Shortsalesdoneright helps homeowners compare a short sale with other options. The right choice must fit your finances after the move, not just remove a listing from your to-do list. A rental that depends on uninterrupted occupancy needs a realistic backup plan.
- Ask an agent for a supported estimate of sale proceeds.
- Compare rental income with the full carrying obligation.
- Ask the servicer about available mortgage assistance.
- Review the practical consequences of managing from another duty station.
Prepare your package
Ask the servicer for its current document checklist before assembling the submission. Common requests include financial statements, income records, bank statements, a hardship explanation, and transaction documents. Requirements depend on the loan and the stage of review.
Keep 3 document groups separate: financial records, military relocation records, and sale documents. Keep copies of everything submitted. Use clear filenames so a request for an updated statement does not trigger a search through unrelated paperwork.
You can organize the package yourself and coordinate it with your agent. For agents outsourcing that work, Shortsalesdoneright prepares the full short-sale package. Homeowners should confirm who owns each task rather than assume the agent and processor have divided it.
- Request the lender’s checklist and required forms.
- Submit complete statements, including required accompanying pages.
- Check names, signatures, dates, and account details.
- Send sensitive records through an approved secure channel.
Track lender requests
Keep a written log of submissions, missing items, and responses. After a call, record the date, contact name, request, and next action. A sent email does not establish that the lender accepted a document as complete.
Ask for a regular status update that distinguishes receipt, review, additional requests, and approval. Those stages mean different things. Shortsalesdoneright provides a dedicated point of contact and weekly lender updates, but updates do not establish an approval date.
Use the short sale timeline guide to understand milestones without treating them as a guaranteed schedule. Your 2026 reporting date still needs its own housing and travel plan.
- Record what was submitted and when.
- Confirm whether the lender received a complete package.
- Assign a person to handle each outstanding request.
- Update financial records when the lender requests them.
Review written terms
An agreement to accept sale proceeds does not automatically answer every question about the unpaid mortgage balance. Read the approval letter and related documents before agreeing to close. Ask a qualified attorney to explain any remaining personal liability and how state law applies.
For a VA-backed mortgage, ask the servicer and VA how the proposed transaction affects the loan and future entitlement. Do not treat lender approval, release of the property lien, release of personal liability, and restoration of VA entitlement as interchangeable.
Get tax advice about any canceled debt. Do not assume a tax exclusion applies simply because the move involves military orders or because another homeowner received different treatment.
- Confirm the approved sale and closing conditions.
- Ask whether any unpaid balance remains your responsibility.
- Review every lienholder’s required terms.
- Take legal and tax questions to qualified professionals.
Coordinate your closing
Plan for a closing that happens after your departure. Ask the closing professional what signing arrangements are acceptable and whether any proposed power of attorney meets the transaction’s requirements. Do not assume a general document will satisfy every participant.
Keep property access, utilities, maintenance, and insurance responsibilities clear through the agreed transfer. If the lender imposes a closing deadline, share it with everyone handling the transaction. Request clarification or an extension before a deadline passes rather than assuming flexibility.
After closing, retain the final settlement documents, lender approvals, and correspondence. Those records help you answer later questions about what the lender accepted and what obligations the documents describe.
- Confirm signing arrangements before leaving the area.
- Assign responsibility for property access and upkeep.
- Check lender deadlines against the closing schedule.
- Keep the final transaction documents together.
The process has separate checkpoints. A complete package starts the review; written terms determine what you are agreeing to; closing completes the approved transaction.
Compare your options before committing
Use this 2026 comparison to decide which option deserves a closer review. The table identifies practical trade-offs, not eligibility or approval. Ask your servicer which assistance options apply to your mortgage before abandoning an option based on a general description.
| Option | Best for | Main benefit | Key limitation |
|---|---|---|---|
| Keep the home | Households able to carry the property after relocation | Preserves ownership without a sale | Mortgage payments and property responsibilities continue |
| Rent the home | Owners with a workable rental budget and management plan | Creates rental income while retaining ownership | Vacancies, repairs, and remote management remain the owner’s responsibility |
| Sell and cover the shortfall | Owners able to fund the difference at closing | Avoids asking the lender to accept reduced proceeds | Requires enough funds for the actual closing shortfall |
| Request mortgage assistance | Owners seeking relief while evaluating whether to keep the home | Allows the servicer to review available assistance | Eligibility and terms depend on the mortgage and circumstances |
| Request a short sale | Owners who need to sell but cannot cover the payoff | Provides a route to request a sale for less than the debt | Requires lender agreement and careful review of remaining obligations |
| Explore a deed in lieu | Owners considering a negotiated transfer to the lender | Offers another possible exit to discuss with the servicer | Lender acceptance, title issues, and remaining liability need review |
Foreclosure is not a negotiated sale option. If you have received foreclosure notices, get legal advice about your deadlines and rights. Submitting a short sale request does not, by itself, establish that a foreclosure process has stopped.
Request help with your short sale
Ask about homeowner options, short-sale processing, and lender negotiation support.
Request help through the appropriate homeowner intake form on the site. Explain your PCS reporting date, loan type, property situation, and any notices already received so the conversation starts with the decisions you need to make.
Common mistakes military homeowners make
Treating PCS orders as automatic approval
Orders establish a required move, not automatic short sale eligibility. Submit the financial explanation and transaction documents the lender requests instead of relying on the orders alone.
Stopping payments to demonstrate hardship
Do not miss payments solely to make a short sale request look stronger. Ask the servicer how payment status affects its review, and get advice before changing your payment plan.
Assuming military protections settle the mortgage
The Servicemembers Civil Relief Act provides protections for qualifying servicemembers, but it does not automatically approve a short sale or cancel mortgage debt. Ask a military legal assistance office or qualified attorney which protections apply to your loan and service dates.
Leaving without a property plan
A lender review can continue after your move. Arrange access, maintenance, insurance, and communication responsibilities before departure so the transaction does not depend on your being physically present.
Reading approval as a complete release
A letter accepting the sale is not a substitute for reviewing its conditions. Get clear advice about the unpaid balance, other liens, tax questions, and VA entitlement where applicable.
FAQ
Can I get a short sale because I have PCS orders?
PCS orders support your explanation for moving, but they do not guarantee short sale approval. Your servicer must review the request under the requirements for your mortgage.
Do I have to fall behind before requesting a military short sale?
Do not assume you must fall behind before asking about a short sale. Ask your servicer which requirements apply to your account before changing mortgage payments.
Can I request a short sale on a VA-backed mortgage?
You can ask your servicer to review a short sale request for a VA-backed mortgage. Ask the servicer and VA about transaction requirements, remaining liability, and future entitlement.
Will a short sale finish before my PCS reporting date?
Your PCS reporting date does not guarantee a short sale closing date. Make a separate relocation plan and confirm how lender requests and signing will be handled after you leave.
Does short sale approval mean I owe nothing afterward?
Short sale approval does not automatically mean every remaining obligation is released. Have a qualified attorney review the written terms and applicable state law before closing.
Does submitting a short sale request stop foreclosure?
Submitting a short sale request does not by itself confirm that foreclosure has stopped. Ask the servicer about the account status and obtain legal advice about notices and deadlines.
Who can help with the lender paperwork during my move?
Shortsalesdoneright provides short-sale processing and lender negotiation support, including a dedicated point of contact and weekly lender updates. Confirm responsibilities with your agent and processor before relocating.
One last thing
Ask about the unpaid balance before you focus on the closing date. A faster closing does not resolve a term you have not understood. For your 2026 move, keep lender conditions, legal advice, and relocation arrangements in separate records so progress in one area does not hide an unresolved issue in another.


